LLC vs S-Corp 2026: Which Saves More on US Taxes (Real Numbers)
If you're running a side hustle pulling in $80K a year, or a two-person consultancy clearing $200K, you've probably heard the same advice from three different people: "Just switch to an S-Corp and you'll save thousands." It's repeated so often it feels like gospel.
But the math isn't that simple in 2026.
This guide breaks down the real tax difference between an LLC and an S-Corp using current IRS numbers, the new 2026 SECA wage base, and a side-by-side calculation at four income levels.
I'll show you exactly where the S-Corp election pays off, where it actually costs you money, and the paperwork most YouTube videos skip over.
LLC vs S-Corp: What's Actually Different for Taxes
Here's the part most articles get wrong.
An LLC and an S-Corp aren't the same kind of thing.
An LLC is a legal entity at the state level.
An S-Corp is a federal tax election.
You can be an LLC that's taxed as an S-Corp.
That's actually the most common setup I see among the founders I work with.
By default, a single-member LLC is taxed as a sole proprietorship.
A multi-member LLC is taxed as a partnership.
Both report on Schedule C or Form 1065, and every dollar of net profit is hit with self-employment tax.
Last March, my college friend Marcus — who runs a three-person Shopify consultancy in Austin called Northbound Commerce — finally pulled the trigger on the S-Corp election after watching his 2024 SE tax bill cross $19,000.
The switch saved him about $7,800 on his 2025 return.
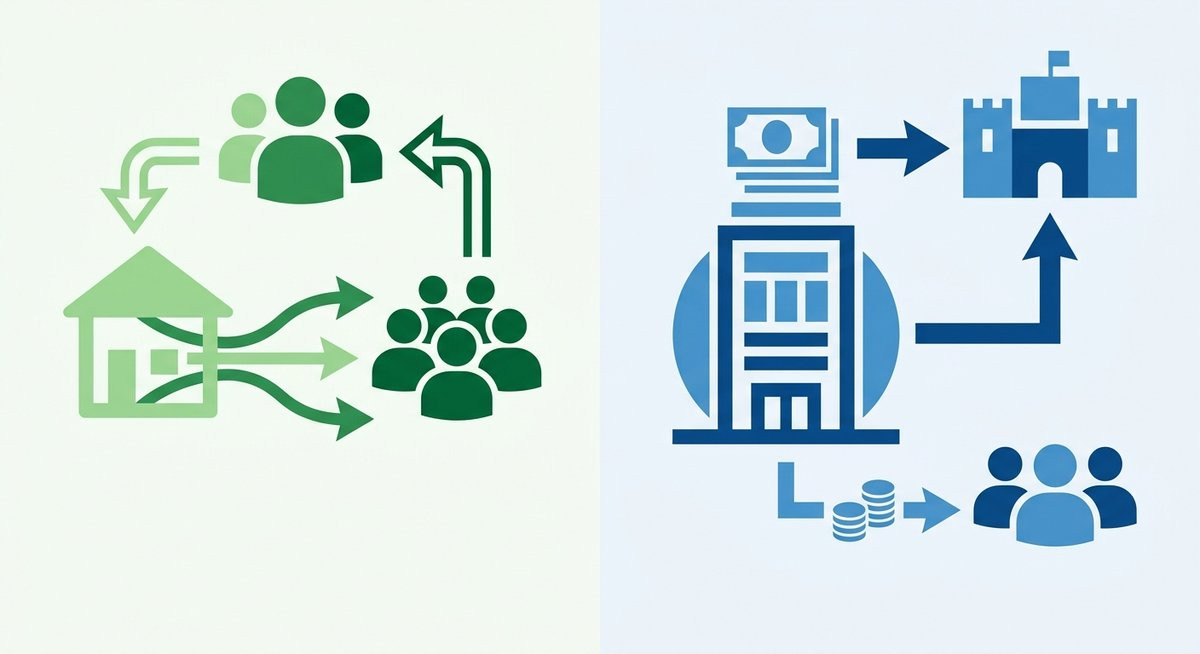
The core mechanical difference: an S-Corp lets you split your business income into two buckets.
One is W-2 salary, which is subject to FICA payroll taxes.
The other is a shareholder distribution, which isn't.
That gap is where the savings come from.
That's it.
The 2026 Self-Employment Tax Math That Drives Everything
You can't compare these two structures without understanding SE tax.
In 2026, self-employment tax is 15.3% on the first $176,100 of net earnings (12.4% Social Security plus 2.9% Medicare), and 2.9% Medicare on everything above that.
According to the Social Security Administration's October 2025 announcement, the wage base climbed from $168,600 in 2025 to $176,100 in 2026 — a 4.4% jump.
High earners get hit with an additional 0.9% Medicare surtax on income above $200,000 single or $250,000 married filing jointly.
That hasn't changed since 2013, but more business owners cross it every year.
Here's how the 2026 rates stack up for a self-employed taxpayer:
| Tax Component | 2026 Rate | Income Cap | Who Pays It |
|---|---|---|---|
| Social Security (SE) | 12.4% | $176,100 | LLC owners on full profit |
| Medicare (SE) | 2.9% | No cap | LLC owners on full profit |
| Additional Medicare | 0.9% | $200K single / $250K MFJ threshold | High earners only |
| S-Corp FICA (on W-2 only) | 15.3% combined | $176,100 Social Security portion | S-Corp shareholders |
| S-Corp Distributions | 0% payroll tax | N/A | S-Corp shareholders |
The IRS does let LLC owners deduct half of their SE tax on Schedule 1, so the effective cost is a little softer than the headline number.
But it still stings.
Side-by-Side: Tax Bills at $75K, $120K, $200K, $350K
Let's run actual numbers.
I'll assume a single-owner business with no employees, a 40/60 salary-to-distribution split on the S-Corp side (which is defensible for most operator-led service businesses), and federal tax only — state tax varies too much to model cleanly.
| Net Business Profit | LLC Total SE Tax | S-Corp Payroll Tax (40% salary) | Annual Savings | Worth Electing? |
|---|---|---|---|---|
| $75,000 | $10,597 | $4,590 | $6,007 | Marginal — fees may eat half |
| $120,000 | $16,955 | $7,344 | $9,611 | Yes, clear win |
| $200,000 | $23,572 | $12,240 | $11,332 | Yes, strong case |
| $350,000 | $28,082 | $21,420 | $6,662 | Yes, but QBI complicates it |
Two things jump out.
The savings peak in the $150K–$250K range.
And at $350K the benefit shrinks because the SS portion of SE tax already capped out — you're only saving the 2.9% Medicare piece on the distribution side, not the full 15.3%.
"Reasonable Compensation" — The IRS Trap Most Owners Miss
This is where S-Corp owners get audited.
The IRS requires you to pay yourself a reasonable salary before taking distributions.
Pay yourself $20,000 on $200,000 of profit and you're inviting trouble.
The IRS has won several high-profile cases on this — Watson v.
United States (2012) is still the one tax attorneys cite, where the court reclassified $175,000 of distributions as wages and slapped on back taxes plus penalties.
What does "reasonable" actually mean? The IRS looks at:
- Comparable salaries in your industry and region (RCReports and BLS data are the go-to references)
- Your training, experience, and the duties you perform
- The time you devote to the business
- What the business could pay someone else to do your job
A useful rule of thumb I picked up from a CPA at a Bay Area firm called Levro: for service-heavy solo operators, salaries usually land between 35% and 60% of net profit.
Capital-intensive businesses (e-commerce with real inventory, agencies with sub-contracted labor) can defend lower percentages because the profit isn't all from your labor.
Hidden Costs of an S-Corp That Eat Your Savings
S-Corp savings on paper rarely match savings in your bank account.
Here's what people forget to subtract:
- Payroll service: Gusto runs $40/month base plus $6 per person. That's about $552/year for a solo S-Corp.
- S-Corp tax return (Form 1120-S): $800–$2,000 depending on your CPA. The national average per a 2025 NSA survey was $923.
- Bookkeeping rigor: S-Corps require cleaner books. Plan on $150–$400/month if you outsource.
- State franchise/excise tax: California hits S-Corps with a $800 minimum tax plus 1.5% on net income. Tennessee, New York, and Illinois have their own surcharges.
- Unemployment insurance: Since you're now an employee of your own corp, federal and state unemployment taxes apply to your wages — roughly $420 to $700 per year.
Add it up: a solo S-Corp typically burns $2,500–$4,000 in compliance overhead annually.
So that $6,007 in tax savings at the $75K profit level? After costs, you're closer to $2,500 in real money.
Not nothing, but not a no-brainer either.
QBI Deduction in 2026: How Section 199A Tilts the Decision
The Qualified Business Income deduction lets pass-through owners deduct up to 20% of qualified business income.
It applies to both LLCs and S-Corps.
For 2026, the IRS has set the income thresholds at $241,950 for single filers and $483,900 for joint filers (these are the inflation-adjusted figures published in Rev.
Proc. 2025-32).
Here's the wrinkle that matters: for S-Corps, only the distribution portion counts toward QBI — your W-2 wages don't.
So paying yourself a higher salary actually shrinks your QBI deduction.
There's an optimization sweet point where lowering your salary increases QBI but raises audit risk.
Most CPAs I've worked with target the lowest defensible salary that still passes the reasonable compensation test.
Specified Service Trades or Businesses (SSTBs) — consultants, attorneys, doctors, financial advisors — start phasing out of QBI above the threshold.
If you're an SSTB making $400K solo, you may lose QBI entirely, which often makes the S-Corp election a closer call.
When an LLC Genuinely Beats an S-Corp
I've talked plenty about S-Corp wins.
Now the cases where staying an LLC is the smarter move:
- Profit under $50,000: Savings won't outrun compliance costs. Don't bother yet.
- Investment or rental real estate: Passive income isn't subject to SE tax in the first place — S-Corp election gains you nothing and complicates basis rules.
- You want maximum retirement contributions: Solo 401(k) contributions for an LLC owner are based on net SE income, while S-Corp contributions are based on W-2 wages only. Lower W-2 = lower retirement room.
- Multiple owners with unequal involvement: S-Corp distributions must be pro-rata to ownership. LLCs let you allocate income flexibly via the operating agreement.
- You take international clients or plan to raise VC: S-Corps can't have non-resident shareholders or institutional investors. The election ends the day a VC term sheet shows up.
One more thing worth saying out loud: if you're not making the salary process bulletproof — meaning real payroll runs every two weeks, W-2 issued in January, quarterly 941s filed — the IRS will not view your "salary" as legitimate.
They'll reclassify everything.
Half-doing it is worse than not doing it.
How to Elect S-Corp Status (Form 2553 Walkthrough)
Once you've run the math and decided to elect, the mechanics are simpler than people think.
You file Form 2553 with the IRS.
The deadline: no later than two months and 15 days after the start of the tax year you want the election to take effect, or any time during the prior year.
For a 2026 election with a January 1 start, you needed to file by March 15, 2026.
Missed it? The IRS routinely grants late-election relief under Rev.
Proc. 2013-30 if you have reasonable cause — I've seen it work for filings as late as October of the same year.
| Step | Action | Cost |
|---|---|---|
| 1 | Form your LLC at the state level (if not already done) | $50–$500 state filing fee |
| 2 | Obtain an EIN from IRS.gov (free, takes 10 minutes online) | $0 |
| 3 | File Form 2553 with the IRS, signed by all members | $0 federal filing |
| 4 | Set up payroll through Gusto, OnPay, or ADP | $40–$80/month |
| 5 | Determine reasonable compensation using BLS or RCReports data | $0–$400 if you buy the report |
| 6 | Process quarterly Form 941 and annual W-2/W-3 filings | Included in payroll service |
Frequently Asked Questions
Q.
At what income level does the S-Corp election usually start paying off?
A.
Most CPAs use $60,000–$80,000 of net profit as the rough breakeven point.
Below that, the $2,500–$4,000 in compliance and payroll costs typically wipe out the SE tax savings.
Once profit clears $100,000, the math gets compelling for most service businesses.
Q.
Can I switch my existing LLC to an S-Corp mid-year?
A.
Yes, but the election will apply to the start of the next tax year unless you qualify for retroactive relief under Rev.
Proc. 2013-30.
You can file Form 2553 with reasonable cause language and request the current year, and the IRS approves these requests in most cases when filed within the same calendar year.
Q.
What happens if the IRS thinks my S-Corp salary is too low?
A.
They can reclassify distributions as wages, which triggers back payroll taxes, interest, and penalties of up to 100% of the unpaid employment tax.
Watson v.
United States is the leading case — the court forced $175,000 of distributions to be treated as W-2 wages.
Use industry compensation data and document your reasoning.
Q.
Does an S-Corp affect my Solo 401(k) contributions?
A.
Yes, and not always favorably.
S-Corp employer contributions are limited to 25% of W-2 wages, while LLC owners can contribute up to 20% of net SE income (about 25% of net earnings after the SE tax adjustment).
Lowering your S-Corp salary to save on payroll tax also lowers your retirement contribution ceiling.
Q.
Can a single-member LLC be an S-Corp?
A.
Absolutely.
A single-member LLC can elect to be taxed as an S-Corp by filing Form 2553.
The LLC remains an LLC for state law purposes (so liability protection and operating agreement still apply), but federally it's treated as an S-Corporation.
This is the most common structure for solo consultants earning over $80,000.
Final Take: Run Your Numbers, Then Run Them Again
The S-Corp election is one of the most useful tools in the small business tax code, but it's not universal.
Last spring I helped my sister-in-law's wedding photography business — Maple & Ivy Studios, based in Charlotte — model whether to elect.
Her net profit was $68,000.
After running the numbers across three scenarios with a $24,000 W-2 baseline, the savings came out to about $3,100 against $3,400 in added compliance costs.
She stayed an LLC.
Two years from now, when her revenue grows, we'll revisit.
Build a real spreadsheet.
Plug in your actual 2025 profit, your defensible salary range, your state's franchise tax, and the cost of payroll.
The break-even line is different for everyone, and the worst outcome is electing because someone on TikTok said you should.
This article is for informational purposes only and does not constitute professional advice.
Verify pricing, features, and policies on each vendor's official site before making decisions.
Disclaimer: This article is for educational purposes only and does not constitute financial, investment, tax, or legal advice.
Consult a licensed professional before making financial decisions.
Figures and rates were accurate as of publication and may change.


Comments
Post a Comment